The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Life insurance in Australia can include death cover, total and permanent disability cover, trauma insurance and income protection. This guide explains how the main types differ and what to consider before comparing quotes.
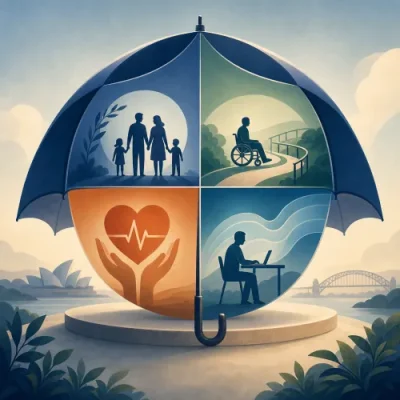
When Australians talk about life insurance, they are often referring to a group of personal insurance products rather than one single policy. The main types of life insurance in Australia are usually death cover, total and permanent disability cover, trauma insurance and income protection.
Each type is designed for a different risk. Some pay a lump sum if you die or become seriously ill or disabled. Others pay a regular monthly benefit if illness or injury stops you from working. Understanding these differences can make it easier to compare options, ask better questions and decide what level of cover may be worth exploring for your circumstances.
This article provides general information only. It does not take into account your objectives, financial situation or needs. Policy availability, premiums, exclusions, benefit limits and eligibility depend on the insurer, policy terms and your personal circumstances.
The main types of life insurance in Australia
In Australia, the phrase "life insurance" is often used as an umbrella term for several types of cover. The four core categories are:
- Death cover: pays a lump sum if the insured person dies or, in many policies, is diagnosed with a terminal illness that meets the policy definition.
- Total and permanent disability insurance: usually called TPD insurance, pays a lump sum if you become totally and permanently disabled and meet the policy definition.
- Trauma insurance: also called critical illness cover, pays a lump sum if you suffer a specified serious medical event covered by the policy, such as certain cancers, heart attacks or strokes.
- Income protection: pays a regular benefit for a period if illness or injury prevents you from working and you meet the policy's claim requirements.
You may see these products offered separately or bundled together. Some people also hold life insurance through their superannuation fund, while others buy cover outside super or use a combination of both.
Quick comparison of life insurance types
| Type of cover |
What it is designed for |
Typical benefit style |
Common use |
| Death cover |
Financial support for beneficiaries if the insured person dies or meets a terminal illness definition |
Lump sum |
Helping family repay debts, cover living costs or maintain financial stability |
| TPD insurance |
Financial support if you become totally and permanently disabled |
Lump sum |
Medical costs, home modifications, debt reduction and long-term living expenses |
| Trauma insurance |
Financial support after a specified serious illness or injury |
Lump sum |
Recovery costs, time away from work, treatment-related expenses and household bills |
| Income protection |
Replacing part of your income if you cannot work due to illness or injury |
Regular monthly benefit |
Ongoing bills, mortgage or rent, and everyday expenses during recovery |
Death cover: protection for the people who rely on you
Death cover is often what people first think of when they hear the term life insurance. It is designed to provide a lump sum to your nominated beneficiaries if you die. Many policies also include a terminal illness benefit, although the exact definition and claim requirements vary between policies.
Death cover may be relevant if other people depend on your income, unpaid care or financial contribution. This may include a partner, children, ageing parents, business partners or anyone who would be financially affected by your death.
People commonly consider death cover for purposes such as:
- repaying a mortgage or other debts;
- covering funeral and estate-related costs;
- helping a partner meet ongoing household expenses;
- funding children's education or care needs;
- providing a financial buffer while family members adjust.
Death cover is commonly available through superannuation as well as outside super. Holding cover through super can affect ownership, premium payment and how benefits are released or taxed, so it is important to read the relevant product disclosure statement and consider professional guidance if you are unsure.
Term life insurance in Australia
The phrase term life insurance Australia usually refers to death cover that applies for a set period or until a specified expiry age, provided premiums continue to be paid and the policy remains in force. In Australia, many retail life insurance policies are structured this way: they provide risk cover rather than building an investment value.
You may also see overseas articles discussing "whole life" or "universal life" insurance. These terms are less central to the current Australian retail life insurance market than death cover, TPD, trauma and income protection. If you come across these terms while researching online, check whether the information is written for Australia before relying on it.
TPD insurance: cover for permanent disability
TPD insurance is designed to pay a lump sum if you become totally and permanently disabled and satisfy the policy definition. This type of cover can be complex because definitions matter.
Some TPD policies use an "own occupation" style definition, which considers whether you can work again in your specific occupation. Others use an "any occupation" style definition, which considers whether you can work again in an occupation suited to your education, training or experience. The wording can significantly affect how a claim is assessed.
TPD cover may help with major financial impacts such as:
- repaying or reducing debts;
- paying for rehabilitation or medical costs not otherwise covered;
- modifying a home or vehicle;
- replacing lost future earning capacity;
- supporting dependants if your ability to work is permanently affected.
TPD insurance is often available inside super, outside super or linked to death cover. Linked cover can sometimes reduce the remaining death benefit if a TPD claim is paid, depending on the policy structure.
Trauma insurance: cover for specified serious illnesses
Trauma insurance, also known as critical illness cover, pays a lump sum if you experience a specified medical event that meets the policy definition. Covered conditions often include serious illnesses such as certain cancers, heart attacks and strokes, but the exact list and definitions vary widely between insurers.
The purpose of trauma cover is not only to replace income. It can provide flexibility at a difficult time, such as helping you reduce work hours, pay treatment-related costs, manage household bills or make changes at home while you recover.
Important features to review include:
- which medical conditions are covered;
- how each condition is defined;
- whether partial benefits apply for some events;
- waiting periods or survival periods;
- exclusions, pre-existing condition rules and claim evidence requirements.
Trauma insurance is generally arranged outside superannuation. This is one reason it is important not to assume that insurance inside super covers every risk you may be concerned about.
Income protection: cover for your ability to earn
Income protection is different from lump sum life insurance. It is designed to pay a regular monthly benefit if you cannot work because of illness or injury and you meet the policy's requirements. The benefit is usually linked to a portion of your income, subject to policy limits and insurer rules.
Income protection policies can differ in several important ways, including:
- Waiting period: how long you must be unable to work before benefits may start.
- Benefit period: how long benefits may continue if you remain eligible.
- Occupation and disability definitions: how the insurer assesses whether you are unable to work.
- Benefit amount and offsets: how benefits interact with other payments or income sources.
- Premium structure: how premiums may change over time.
Income protection can be held through super or outside super, although the features available may differ. For example, policies held through super must generally align with superannuation rules, which may affect definitions and access to benefits.
Standalone, linked and bundled cover
Life insurance products can be structured in different ways. You might hold one type of cover by itself, or several covers under one policy package. The structure can affect cost, flexibility and how claims interact.
- Standalone cover means the benefit is separate from your other covers.
- Linked cover means one benefit may be connected to another. For example, a TPD or trauma claim may reduce the remaining death cover if the policy is structured that way.
- Bundled cover means multiple cover types are arranged together, often under one policy or application process.
There is no single structure that suits everyone. A lower premium arrangement may involve trade-offs, while a more flexible structure may cost more. Always check how benefits interact before choosing cover.
Life insurance inside super versus outside super
Many Australians first receive life insurance through their superannuation fund. Insurance inside super can be convenient because premiums are generally deducted from your super balance rather than your personal bank account. However, it may not provide the same level of flexibility or range of cover as a policy held outside super.
Key differences to consider include:
- Ownership: inside super, the trustee owns the policy on behalf of members; outside super, you usually own the policy directly.
- Premium payment: inside super, premiums may reduce your retirement savings; outside super, premiums are usually paid from your own cash flow.
- Cover types: death, TPD and income protection may be available through super, while trauma cover is generally arranged outside super.
- Benefit release: insurance inside super may need to satisfy both the insurer's policy terms and superannuation release rules.
- Tax treatment: tax outcomes can differ depending on ownership, beneficiary type and policy structure.
If you already have cover in super, review the amount, definitions and exclusions before assuming it is enough for your needs.
How to think about the right mix of cover
Choosing between the types of life insurance in Australia is not just about picking a product name. It is about identifying the financial risks you want to plan for.
Useful questions include:
- Who depends on your income, care or financial contribution?
- What debts would need to be repaid or managed if you died or could not work?
- How long could your household meet expenses without your income?
- Would you need a lump sum, a monthly benefit or both?
- Do you already have insurance through super?
- Are there exclusions, loadings or pre-existing condition terms that may affect you?
- How would premiums fit into your budget over time?
If you are estimating how much cover may be appropriate, a calculator can help you organise the numbers before you compare quotes. You can explore available tools on the Life Insurance Online calculators page.
What affects eligibility and premiums?
Insurers usually assess applications through underwriting. This process may consider factors such as your age, occupation, health history, smoking status, pastimes, income, requested cover amount and policy features. The outcome can vary between insurers.
Depending on your circumstances and the insurer's criteria, an offer of cover may include standard terms, exclusions, a premium loading, a reduced benefit, or the insurer may decide not to offer cover. This is why it can be useful to compare policy features rather than focusing only on the headline premium.
Before applying, it is important to answer insurer questions accurately. Non-disclosure or incorrect information can affect future claims.
How to compare life insurance options
When comparing policies, look beyond the product label. Two policies with the same type of cover can operate quite differently.
Consider comparing:
- covered events and definitions;
- exclusions and waiting periods;
- premium type and how premiums may change;
- indexation or cover increase options;
- policy ownership and beneficiary arrangements;
- how linked benefits affect one another;
- claim requirements and supporting evidence;
- features available inside or outside super.
You can start by reviewing the life insurance options available through Life Insurance Online. If your circumstances are complex, or you are unsure how different policy types work together, you may also wish to seek personalised guidance from a licensed professional. The brokers page can help you understand the support available.
Common mistakes to avoid
- Assuming all life insurance is the same: death cover, TPD, trauma and income protection respond to different events.
- Only comparing premiums: cheaper cover may have narrower definitions, fewer features or exclusions that matter to you.
- Ignoring superannuation cover: you may already have some cover, but it may not be enough or may not include every type you need.
- Overlooking policy definitions: definitions are especially important for TPD, trauma and income protection claims.
- Not reviewing cover over time: major life events such as buying a home, having children, changing jobs or reducing debt can change your insurance needs.
Bottom line
The main types of life insurance in Australia are designed to protect against different financial risks. Death cover supports beneficiaries if you die, TPD insurance responds to permanent disability, trauma insurance provides a lump sum for specified serious illnesses, and income protection helps replace income if illness or injury stops you from working.
Understanding these categories can make it easier to compare policies and decide which questions to ask before requesting quotes. The right mix of cover depends on your personal circumstances, financial commitments, family situation, health, budget and the insurer's terms.
Published: Tuesday, 6th Oct 2026
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.